Juncker and tax haven Luxembourg. We won’t tire of repeating this one. Hat tip: David Walch
We have often remarked how international tax haven blacklists generally reflect the political powers and influence of nation states; as a result they tend to include ‘minnows’ but not the big fish. (Among other things, this means a lot of econometric studies resting on a baseline of nonsense.)
So The Guardian‘s headline yesterday illustrates our point exactly. We’ve partly plagiarised its headline Tax haven blacklist omits Luxembourg as Brussels announces reform plans, which kind of tells the whole story. Yesterday’s huge Walmart story involving Luxembourg just emphasises the point.
Now the EU list is here. Note a few other secrecy jurisdictions or tax havens that are absent.
Switzerland, for instance, ranked Number 1 on the Financial Secrecy Index (the only international ranking that does not use political criteria). The United Kingdom, which on some measures is the world’s most important. (They have, at least, tapped several UK Overseas Territories and Guernsey, but not Jersey. Take a look at this on Jersey). And, finally, what about the United States?
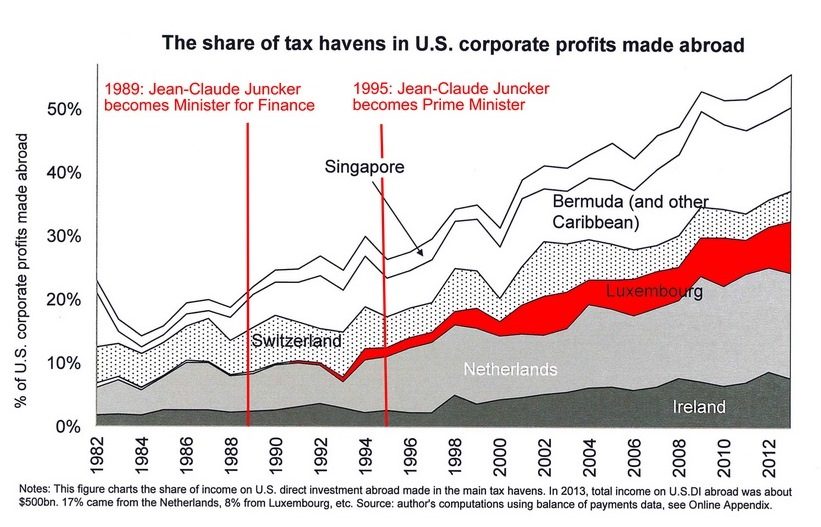
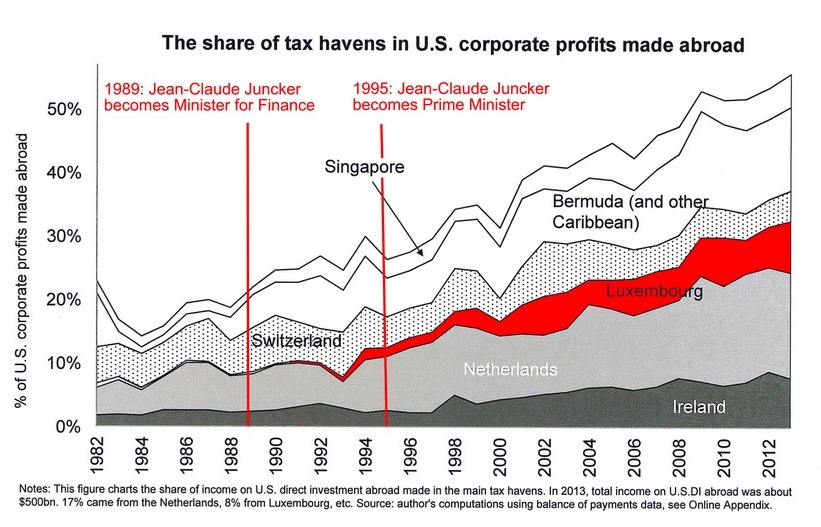
This blog, however, is really just an opportunity to reproduce a graph that we’ve deployed before, highlighting the role of the European Commission president, Jean-Claude Juncker, as the architect of the abusive Luxembourg tax haven. Click to enlarge the graph.
We won’t tire of wheeling this graph out periodically as a reminder of what everyone in Luxembourg tax circles, and many Europeans, already know.
The author

Related articles
UN tax convention hub – updates & resources
UN Framework Convention – Roundup of the Fifth Session of Negotiations
Notes on the UN tax convention draft protocol on dispute prevention and resolution
11 September 2026
The European Court of Justice strikes against transparency again. Our response should be to call for an end to corporate limited liability
Report of the Fifth Session of negotiations on the UN tax convention
4 September 2026
Submission to Workstream I on Co-Lead’s Zero Draft of UN Framework Convention on International Tax Cooperation (post-Fifth Session)
28 August 2026
Submission to Workstream II on Taxation of Income from Cross-Border Services (post-Fifth Session)
26 August 2026
Strengthening public resource mobilization through tax justice
25 August 2026
Submission to Workstream III on Dispute Prevention and Resolution (post-Fifth Session)
24 August 2026
From data to policy: Building Africa’s evidence ecosystem for better tax reform